Beyond the Pitch Deck: Author Dr. Bitan Ghosh Introduces an Evidence-Based Framework for Startup Evaluation and Investment Decisions in Elevent Index: From Pitch Deck to Investment Decisions
 BMRD
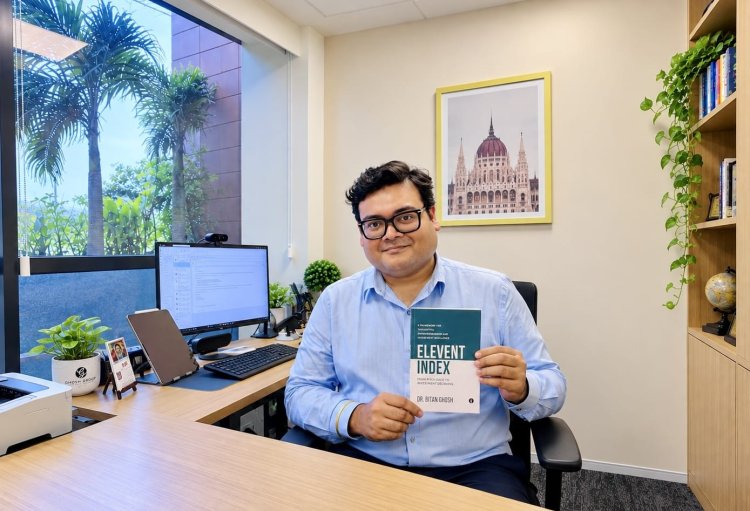
In a startup ecosystem where founders compete for capital and investors navigate increasingly complex investment opportunities, distinguishing a promising business from an investment-ready one remains a significant challenge. In Elevent Index: From Pitch Deck to Investment Decisions, Author Dr. Bitan Ghosh introduces an integrated framework designed to bring greater structure, clarity, and consistency to startup evaluation and fundraising. The book addresses a persistent gap between how startups present themselves and what the underlying evidence reveals about their business strength and preparedness for investment.
At the heart of the book is the Elevent Index framework, which evaluates three interconnected concepts: Investment Quality, Funding Readiness, and Capital Readiness. The Investment Quality Score (IQS) assesses a startup across eleven dimensions and 110 sub-parameters, while the Funding Readiness Score (FRS) examines five additional dimensions and 50 sub-parameters. Together, these contribute to the Capital Readiness Score (CRS), bringing 160 evidence-based assessment points into a unified framework. Drawing on assessments and interactions involving more than 2,000 startups, the book distinguishes between the fundamental quality of a business and its preparedness to raise and deploy capital effectively.
Through anonymised case studies, diagnostic checklists, worked calculations, and practical guidance, Author Dr. Bitan Ghosh demonstrates how structured assessment can help founders identify weaknesses, enable investors to evaluate opportunities more consistently, and create a common language for investment discussions. From uncovering misleading financial indicators to examining market accessibility and deteriorating unit economics, the book emphasises a central principle: investment decisions should be grounded in evidence rather than ambition or presentation alone. By combining structured analysis with human judgment, Elevent Index: From Pitch Deck to Investment Decisions offers a practical approach to improving the relationship between startups and the capital they seek.
1. Can you provide an overview of your book and how it addresses key challenges in the world today?
My book, Elevent Index: From Pitch Deck to Investment Decisions, is fundamentally about improving the way startups are understood, evaluated, prepared for investment, and ultimately funded. I wrote it because I felt there was a persistent gap in the startup ecosystem. Every day, thousands of founders seek capital, yet the process of determining which businesses are genuinely investment-worthy remains surprisingly fragmented.
Investors often rely on experience, instinct, pattern recognition, financial projections, founder presentations, or internal checklists. Each of these has value, but individually they provide only part of the picture.
The book introduces Elevent Index as an integrated framework for evaluating three separate but interconnected concepts: Investment Quality, Funding Readiness, and Capital Readiness. The Investment Quality Score, or IQS, examines the fundamental strength of a startup across eleven dimensions and 110 sub-parameters. The Funding Readiness Score, or FRS, evaluates five additional dimensions and 50 sub-parameters to determine whether the organisation is actually prepared to raise capital. Together, these produce a Capital Readiness Score, or CRS. In total, the framework examines 160 evidence-based assessment points.
The larger challenge I am trying to address is the gap between perception and evidence. A compelling pitch does not necessarily mean there is a compelling business behind it, while a genuinely strong startup may fail to communicate its strengths effectively enough to attract capital. I wanted to create a common language through which founders, investors, accelerators, advisors, and investment committees could discuss startups more systematically.
Importantly, the book does not argue that investment decisions should become mechanical. In fact, I make the opposite argument. Human judgment remains essential. What the framework does is discipline that judgment by ensuring that important questions are not overlooked simply because a founder is charismatic, a particular sector is fashionable, or one impressive metric dominates the conversation.
In that sense, I see the book as being about better decision-making as much as it is about startups. Capital is a scarce resource. When it is allocated more thoughtfully, strong businesses have a better opportunity to grow, investors can make more defensible decisions, and the wider entrepreneurial ecosystem becomes more efficient.
2. What inspired you to write this book, and what specific expertise or experiences do you bring to the subject matter?
The inspiration came from repeatedly seeing the same problem from both sides of the fundraising table. I had spent years advising founders and preparing them to raise capital while, at the same time, participating in the evaluation of startups from an investment perspective. What kept troubling me was a deceptively simple question: What specifically makes one startup ready for capital while another, sometimes outwardly similar startup, is not?
I found that experienced people often had very different answers. One investor might emphasise the founder, another the market, another financial performance, and another execution capability. All of these perspectives could be valid, but none of them individually offered a complete explanation. I also saw fundamentally strong companies struggle with fundraising because of correctable issues such as a messy cap table, weak financial reporting, incomplete legal documentation, unclear valuation logic, or a data room assembled at the last minute.
Elevent Index therefore began not as an academic exercise but as a working habit. I had been informally assessing companies across recurring categories for years. At one point, during a discussion with an investment committee, I was challenged on why the discipline I used mentally had never been properly documented. That question stayed with me. I subsequently spoke with founders as well, and their frustration was often the mirror image of the investor's problem. Many founders could accept being rejected; what they found difficult was being rejected without knowing specifically what needed improvement.
That became the intellectual starting point of the framework. What began with eleven investment quality dimensions eventually expanded when I recognised that business quality and fundraising preparedness were not the same thing. This led to the five Funding Readiness dimensions and ultimately the integrated Capital Readiness architecture. The framework was refined through assessments, investment discussions, accelerator relationships, and founder interactions involving more than two thousand startups across different stages, sectors, and markets.
So, the experience I bring to the subject is not simply theoretical. It comes from observing how founders prepare, how investors assess, how due diligence unfolds, where transactions become difficult, and where otherwise promising companies lose momentum. The book is my attempt to convert those accumulated observations into something structured, teachable, repeatable, and useful to people beyond my own decision-making process.
3. Could you share some of the most valuable insights or takeaways that readers can expect from your book?
One of the most important insights in the book is that a good startup and an investable startup are not necessarily the same thing. A company may have a strong founder, an interesting product, and a genuine customer problem, yet still be unprepared for capital because its financial reporting, governance, documentation, business model, or due diligence readiness is inadequate. Conversely, a startup can have an excellent pitch deck and highly organised fundraising materials while the underlying business remains weak.
That distinction leads to what I consider the central conceptual idea in the book: Investment Quality and Funding Readiness must be evaluated separately before they are considered together. The Investment Quality Score asks whether the business deserves capital. The Funding Readiness Score asks whether the organisation is actually prepared to raise that capital. Capital Readiness emerges only when both are considered together.
A second takeaway is that startup assessment must be stage-sensitive. It makes little sense to evaluate an idea-stage venture using the same expectations we would apply to a scale-up preparing for institutional capital. At the earliest stages, founder capability, market opportunity, and product potential naturally carry greater significance. As the company matures, financial controls, governance, operational scalability, unit economics, and institutional discipline become progressively more important.
A third principle is something I repeat throughout the book: score the evidence, not the ambition. Founders must be ambitious; entrepreneurship almost requires it. But ambition cannot substitute for evidence. An investment process should look at demonstrated execution, customer behaviour, financial data, documents, governance practices, market validation, and observable capability rather than relying only on confidence or narrative strength.
Finally, I want readers to understand that a structured framework does not replace intuition. It improves intuition. When experienced judgment is repeatedly tested against evidence, it becomes more disciplined. My objective is not to make investing mechanical. It is to make important decisions more consistent, explainable, comparable, and ultimately more thoughtful.
4. Can you highlight any case studies or real-world examples from your book that illustrate the principles you discuss?
The book contains a number of “Case in Point” examples designed to show how the principles of Elevent Index operate in practical situations. These are intentionally anonymised, composite cases constructed from patterns observed across founder and investor experiences rather than identifiable individual companies. I made that decision because I wanted readers to learn from real recurring situations without compromising the confidentiality of any founder, investor, or organisation.
One example involves a company that appeared exceptionally well prepared for investment. The founder was articulate, the data room was meticulously organised, and the entire fundraising process initially created a strong impression. But during deeper financial due diligence, an analyst discovered that the company's reported net revenue retention excluded a category of churned enterprise accounts. When the number was reconstructed from the underlying contract data, it fell materially. The business was not necessarily bad, but the underlying reality was weaker than the presentation suggested. The investment was ultimately restructured at a lower valuation with milestone-based tranches. The lesson is that preparation and substance must be assessed separately.
Another case concerns a startup presenting a market opportunity of approximately forty-seven billion dollars. The number itself was legitimate, but the company's product could realistically serve only a small subset of that overall market. Once the serviceable and realistically obtainable market was examined, the opportunity looked very different. That example demonstrates why headline TAM figures should never substitute for a careful analysis of market accessibility and actual demand.
I also discuss a company whose revenue had been growing strongly, giving investors an apparently attractive story. A structured review revealed that customer acquisition cost had almost tripled while customer lifetime value remained flat. Revenue was rising, but the economics supporting that growth had deteriorated. The founder himself eventually acknowledged that he had been watching the wrong line on the chart.
These examples are important because they show why Elevent Index is diagnostic rather than merely numerical. The objective is not simply to produce a score. It is to identify precisely which part of the business deserves confidence and which part needs intervention.
5. Are there any particular challenges or obstacles you encountered while writing this book, and how did you overcome them?
The greatest challenge was converting something that had developed through years of experience and pattern recognition into a framework that another person could actually use consistently. It is relatively easy to say that an experienced investor “knows a good company when they see one.” It is much harder to unpack that judgment into specific dimensions, sub-parameters, evidence requirements, stage-based weightages, formulas, and diagnostic interpretations without losing the nuance that made the original judgment valuable.
That was one reason the framework took time to evolve. The earliest version consisted only of what eventually became the eleven Investment Quality dimensions. Over time, I realised that this alone was insufficient because some fundamentally strong businesses still struggled to raise capital. That led me to separate Funding Readiness into five additional dimensions. The framework ultimately moved from eleven dimensions and 110 sub-parameters to sixteen dimensions and 160 sub-parameters. During that process, weightages were discarded, dimensions were rewritten, and assumptions were challenged whenever real cases did not support the theoretical structure.
Another challenge was maintaining a balance between rigour and usability. A framework with 160 assessment points can easily become overly technical. I therefore worked hard to ensure that the book does not read simply as a scoring manual. It includes founder perspectives, investor psychology, examples, diagnostic checklists, sector variations, worked calculations, a Capital Readiness Matrix, and practical guidance so that readers can understand not just how a score is produced, but why it matters.
Confidentiality was another important consideration. The framework grew from real assessments and real conversations involving founders, investors, accelerator partners, and investment committees. I did not want the educational value of those experiences to come at the expense of anyone's privacy. That is why the book uses anonymised and recombined composite case studies rather than naming identifiable companies.
Ultimately, I overcame these challenges through iteration. The framework became stronger whenever someone pointed out that a weight did not hold up, a category was incomplete, or an example exposed a weakness in the structure. I think that process is appropriate for a book about entrepreneurship: the framework itself had to learn, adapt, and improve in much the same way that I expect founders to.
6. What do you hope readers will gain from reading your book, and how do you envision it making a positive impact on their lives?
My biggest hope is that readers come away with greater clarity. For founders, I want the book to replace the vague question “Am I ready to raise capital?” with a much more useful set of questions: Where is my company genuinely strong? Where am I relying on narrative rather than evidence? Which weaknesses are fundamental to the business, and which are simply readiness gaps that can be corrected before I enter the market for capital?
I describe the book as both a mirror and a roadmap for founders. The mirror matters because entrepreneurship can make self-assessment difficult. Founders naturally become emotionally invested in their businesses. A structured assessment can reveal weaknesses that enthusiasm sometimes hides. The roadmap matters because identifying a weakness is useful only if the founder also understands what to do about it.
For investors, I hope the book provides a disciplined structure around experience. It does not ask investors to abandon judgment. Instead, it provides a common architecture that can make investment committee discussions more consistent and disagreements more productive. Two people may still disagree about a startup, but instead of simply saying “I like the founder” or “I don't like the market,” they can identify the specific evidence behind their disagreement.
For accelerators, incubators, universities, family offices, and advisors, I hope Elevent Index becomes a shared language. One of the recurring problems in startup ecosystems is that founders and investors sometimes appear to be discussing the same company while actually using very different definitions of readiness. The framework gives both sides a common vocabulary.
At a broader level, I would like the book to contribute to a healthier relationship between entrepreneurship and capital. Better founders should be able to understand what investors need to see. Better investors should be able to explain why they reached a particular decision. If both happen, fewer good businesses should be overlooked merely because their founders are less polished, and fewer weak businesses should attract capital merely because they are presented exceptionally well.
That is the positive impact I ultimately hope for: better founders, better investors, better decisions, and, as the book's positioning expresses it, a better future built through more thoughtful entrepreneurship and capital allocation.
7. In a rapidly changing environment, how does your book stay relevant and adaptable for readers over time?
I deliberately designed Elevent Index around principles rather than temporary trends. Technologies will change, investment themes will change, sectors will move in and out of favour, valuation environments will change, and the language founders use in pitch decks will certainly change. But the fundamental questions behind investment decisions remain remarkably persistent: Is the team capable? Is the market real and accessible? Does the product create genuine value? Does the business model work? Are the financials credible? Is the company governed responsibly? Can the organisation withstand due diligence? And is it actually prepared to receive and deploy capital?
The framework remains adaptable because it is stage-sensitive and evidence-based. The same startup should not be evaluated identically throughout its life. An idea-stage company may legitimately have limited financial history and governance infrastructure, while those same gaps would be serious concerns in a scale-up. Elevent Index adjusts the relative importance of dimensions as the company evolves rather than forcing every business through a static checklist.
I also emphasise throughout the book that evidence should take priority over labels. Startup journeys are rarely linear. A company may move forward, stall, pivot, or even return functionally to an earlier stage of validation. That is why the framework determines maturity through demonstrated evidence rather than simply through company age or the name of its latest funding round.
Another important source of adaptability is that the methodology is not presented as an unquestionable constant. Even the 70:30 weighting between Investment Quality and Funding Readiness is discussed with appropriate limitations. The book explicitly recognises that particular investment committees may test the methodology against their own portfolio data and make disciplined adjustments where their evidence supports doing so.
For me, that is an important philosophical point. A framework designed to encourage evidence-based decision-making should itself remain open to evidence.
So, I do not expect readers to treat Elevent Index as a rigid rulebook. I want them to treat it as an architecture for asking better questions. Markets will evolve, technologies will evolve, and new business models will emerge. But if readers continue to evaluate evidence carefully, adjust expectations to the company's stage, distinguish business quality from fundraising preparedness, and use structure to support rather than replace human judgment, the framework can remain relevant even as the startup ecosystem around it changes.
For startup founders preparing to raise capital, investors evaluating opportunities, and accelerators and advisors supporting entrepreneurial growth, the book offers a practical framework for asking better questions, examining evidence, and making more informed decisions. Its central message is clear: sound investment decisions require more than a compelling story; they require a thorough understanding of the business behind it.
Order your copy of Elevent Index: From Pitch Deck to Investment Decisions by Author Dr. Bitan Ghosh on Amazon today and discover a structured approach to evaluating startups, strengthening funding readiness, and making more informed investment decisions.